ANDREW MACRAE

Mortgage experience you can rely on

Creative Mortgage Solutions & Exceptional Service
LET'S TALK

Mortgage financing can be frustrating

It doesn't have to be with these 3 easy steps

Get started right away

The best place to start is to connect with me directly. The mortgage process is personal. My commitment is to listen to all your needs, assess your financial situation, and provide you with a clear plan forward.

Get a clear plan

Sorting through all the different mortgage lenders, rates, terms, and features can be overwhelming. Let me cut through the noise, I'll outline the best mortgage products available with your needs in mind.

Let me handle the details

When it comes time for arranging your mortgage, trust that I will make it happen. I'll make sure you know exactly where you stand at all times. No surprises. I've got you covered.


Everything you need, all in one place

As a trusted mortgage provider, I can help you with the following:

  • Home Purchase
  • Mortgage Refinance
  • Mortgage Renewals
  • First Time Home Buyers
LET'S TALK
Are you ready to buy a new home, refinance, or renew an existing mortgage? Start your application now.

APPLY NOW

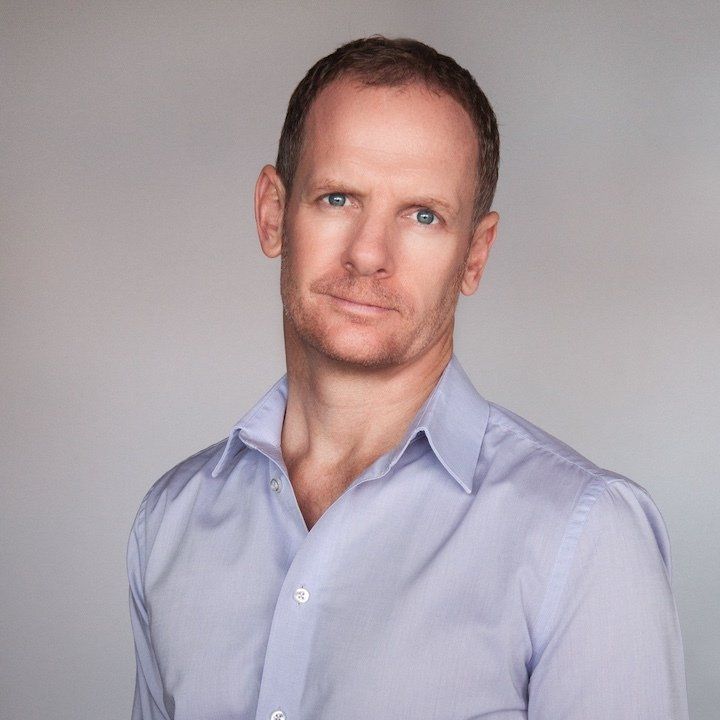
Andrew Macrae

Founding Partner / Mortgage Expert

ANDREW MACRAE

Thanks for visiting my website, I’m a partner and mortgage professional with Bluetree Mortgages WEST, working out of Kelowna since 2009. My office is located near the city centre on Clement Avenue however I’m also happy to assist you over the phone or by email, whatever is most convenient.


As a mortgage broker I can provide you with access to a wide range of lenders including banks, trust companies, credit unions and mortgage specific lenders. Once we decide on a structure, my team will source the best rates and terms for approval and coordinate all the lender paperwork on your behalf. In almost all scenarios the lender compensates me directly so you receive the advice and service of a licensed mortgage professional, access to the best available rates, all at no cost to you.


I look forward to helping you with your next mortgage! 

LET'S TALK
What people say about working with me
John Doe's Image
My wife and I worked with Andrew to purchase our second home. Not being the most experienced or savvy home buyer, I came with a lot of questions, and needed a great deal of guidance. Andrew always took the time to thoughtfully explain every aspect of the mortgage process. No question was too silly, and his recommendations were always in our best interest. There was never a moment where we didn’t feel completely cared for. Highly recommended. Thank you Andrew!

Brad Marshall

John Doe's Image
We’ve had the pleasure of dealing with Andrew for three mortgages.  We wouldn’t even consider going elsewhere and certainly not to a bank.  He works tirelessly to get us the best rate possible with the best possible terms.  He’s professional, reliable, courteous, confidential, and efficient and as an added bonus when we sign papers we often get to snuggle with his coolest dog ever, Morten .  We’ve been so confident working with Andrew we referred him to our kids who have also used his services twice! Thank you again Andrew for your excellent work!

Leslie and Barry Smith

John Doe's Image
My wife and I feel fortunate to have  had Andrew  broker several mortgage transactions for us. I  recommend Andrew as a highly knowledgeable and competent mortgage broker. He is  experienced, has strong relationships within his profession and understands the fine points of the real estate trends, market values and financing options. He is  thorough and  works  hard to ensure his client`s interests are well looked after.

 Calvin and Tamara Kettner

Articles
By Andrew Macrae • October 29, 2026
Owning a home feels great—carrying a large mortgage, not so much. The good news? With the right strategies, you can shorten your amortization, save thousands in interest, and become mortgage-free sooner than you think. Here are four proven ways to make it happen: 1. Switch to Accelerated Payments One of the simplest ways to reduce your mortgage faster is by moving from monthly payments to accelerated bi-weekly payments . Instead of 12 monthly payments a year, you’ll make 26 half-payments. That works out to the equivalent of one extra monthly payment each year, shaving years off your mortgage—often without you noticing much difference in your budget. 2. Increase Your Regular Payments Most mortgages allow you to boost your regular payment by 10–25%. Some even let you double up payments occasionally. Every extra dollar goes directly toward your principal, which means less interest and faster progress toward paying off your balance. 3. Make Lump-Sum Payments Depending on your lender, you may be able to make lump-sum payments of 10–25% of your original mortgage balance each year. This option is ideal if you receive a bonus, inheritance, or other windfall. Applying a lump sum directly to your principal immediately reduces the interest charged for the rest of your term. 4. Review Your Mortgage Annually It’s easy to put your mortgage on auto-pilot, but a yearly review keeps you in control. By sitting down with an independent mortgage professional, you can check if refinancing, restructuring, or adjusting terms could save you money. A quick annual review helps ensure your mortgage is always working for you—not against you. The Bottom Line Paying off your mortgage early doesn’t require a massive lifestyle change—it’s about making smart, consistent choices. Whether it’s accelerated payments, lump sums, or regular reviews, every step you take helps reduce your debt faster. If you’d like to explore strategies tailored to your situation—or want a free annual mortgage review—let’s connect. I’d be happy to help you find the fastest path to mortgage freedom.
By Andrew Macrae • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
By Andrew Macrae • October 15, 2026
Can You Get a Mortgage If You Have Collections on Your Credit Report? Short answer? Not easily. Long answer? It depends—and it’s more common (and fixable) than you might think. When it comes to applying for a mortgage, your credit report tells lenders a story. Collections—debts that have been passed to a collection agency because they weren’t paid on time—are big red flags in that story. Regardless of how or why they got there, open collections are going to hurt your chances of getting approved. Let’s break this down. What Exactly Is a Collection? A collection appears on your credit report when a bill goes unpaid for long enough that the lender decides to stop chasing you—and hires a collection agency to do it instead. It doesn’t matter whether it was an unpaid phone bill, a forgotten credit card, or a disputed fine: to a lender, it signals risk. And lenders don’t like risk. Why It Matters to Mortgage Lenders? Lenders use your credit report to gauge how trustworthy you are with borrowed money. If they see you haven’t paid a past debt, especially recently, it suggests you might do the same with a new mortgage—and that’s enough to get your application denied. Even small collections can cause problems. A $32 unpaid utility bill might seem insignificant to you, but to a lender, it’s a red flag waving loudly. But What If I Didn’t Know About the Collection? It happens all the time. You move provinces and miss a final utility charge. Your cell provider sends a bill to an old address. Or maybe the collection is showing in error—credit reports aren’t perfect, and mistakes do happen. Regardless of the reason, the responsibility to resolve it still falls on you. Even if it’s an honest oversight or an error, lenders will expect you to clear it up or prove it’s been paid. And What If I Chose Not to Pay It? Some people intentionally leave certain collections unpaid—maybe they disagree with a charge, or feel a fine is unfair. Here are a few common “moral stand” collections: Disputed phone bills COVID-related fines Traffic tickets Unpaid spousal or child support While you might feel justified, lenders don’t take sides. They’re not interested in why a collection exists—only that it hasn’t been dealt with. And if it’s still active, that could be enough to derail your mortgage application. How Can You Find Out What’s On Your Report? Easy. You can check it yourself through services like Equifax or TransUnion, or you can work with a mortgage advisor to go through a full pre-approval. A pre-approval will quickly uncover any credit issues, including collections—giving you a chance to fix them before you apply for a mortgage. What To Do If You Have Collections Verify: Make sure the collection is accurate. Pay or Dispute: Settle the debt or begin a dispute process if it’s an error. Get Proof: Even if your credit report hasn’t updated yet, documentation showing the debt is paid can be enough for some lenders. Work With a Pro: A mortgage advisor can help you build a strategy and connect you with lenders who offer flexible solutions. Collections are common, but they can absolutely block your path to mortgage financing. Whether you knew about them or not, the best approach is to take action early. If you’d like to find out where you stand—or need help navigating your credit report—I’d be happy to help. Let’s make sure your next mortgage application has the best possible chance of approval.
Show More